SA data on production
The South African economy has been struggling since the Global Financial Crisis of 2008/09. The years that followed included the lost decade of state capture, the Covid-19 shock, severe supply-side constraints in energy and logistics, as well as the inflation shock following Russia’s invasion of Ukraine. On the production side of the macro economy, we have struggled to grow and create jobs.
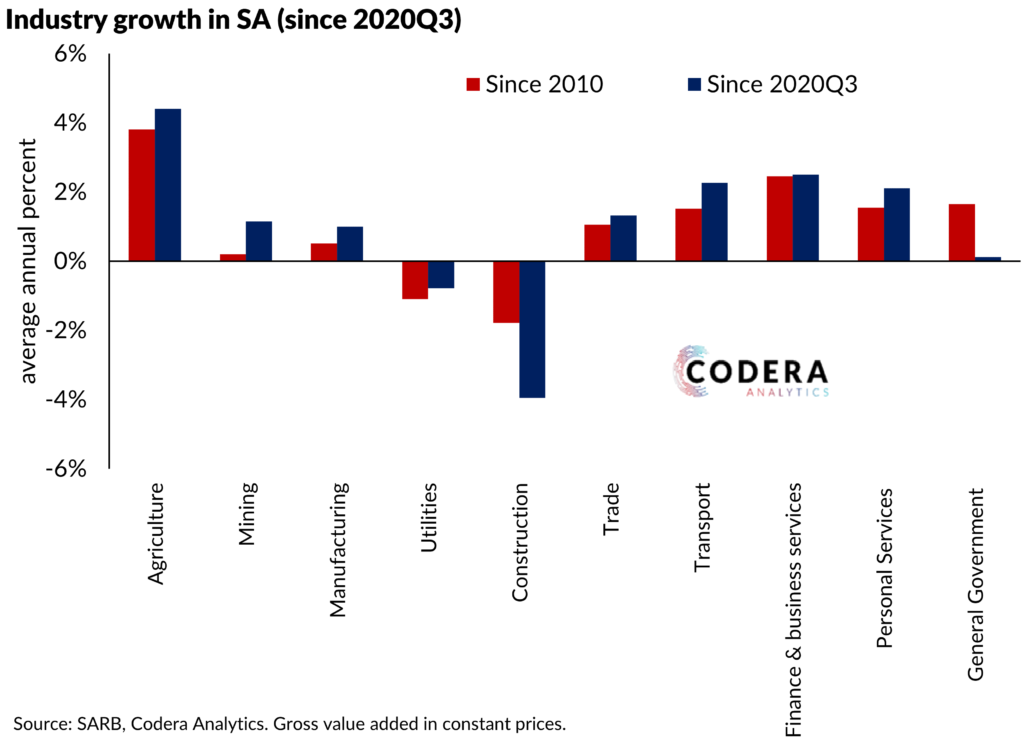
Since 2010, industry value added grew fastest in agriculture and finance, real estate and business services. Several industries shrank, notably mining, electricity, gas and water and construction. Although overall growth has been lower since the COVID-19 pandemic than for the period since 2010, some industries have experienced a slight pickup over the more recent period.

South Africa is a services economy, and a small share of jobs are still in Agriculture, Mining and Manufacturing.
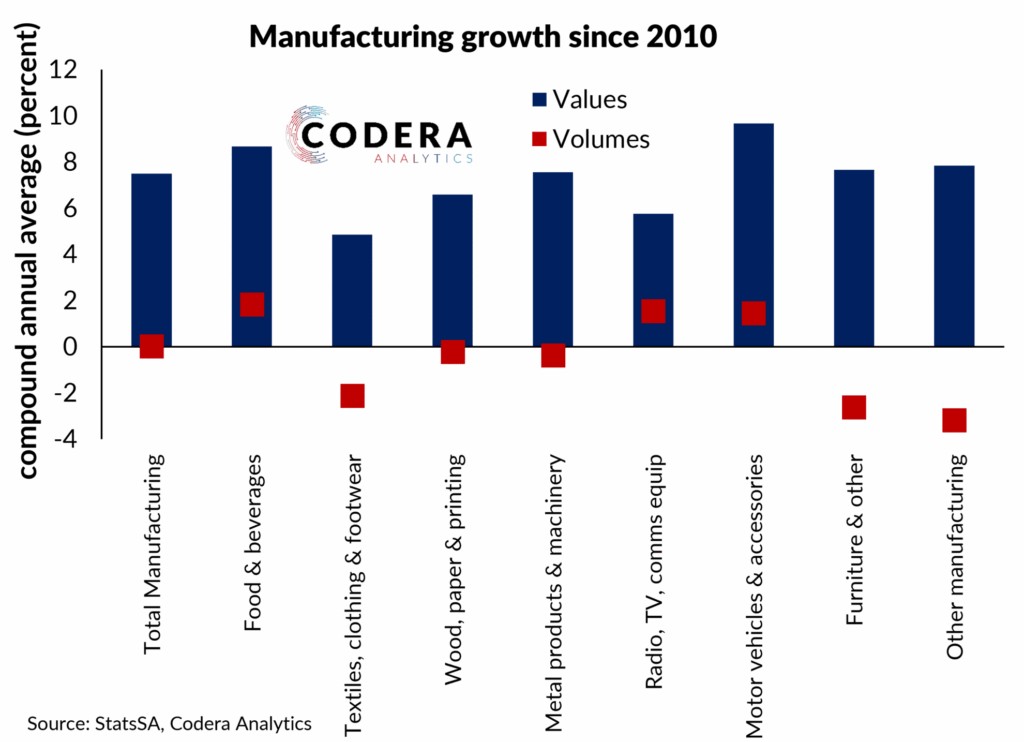
Manufacturing in particular has struggled. Growth in the nominal value of production (which includes inflation) has been positive, but not spectacular. Very low ingrowth, or even contractions in the volume of production is very worrying.
Since 2010, industry value added grew fastest in agriculture and finance, real estate and business services. Several industries shrank, notably mining, electricity, gas and water and construction. Although overall growth has been lower since the COVID-19 pandemic than for the period since 2010, some industries have experienced a slight pickup over the more recent period.
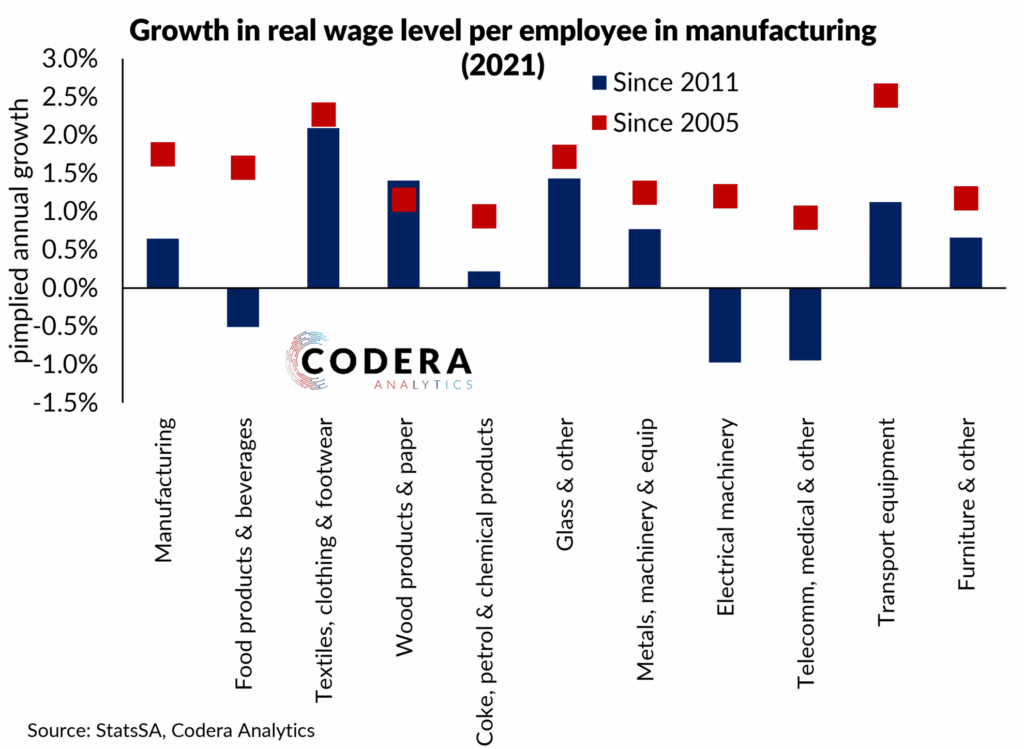
If an industry does not grow, wages stagnate. The following figure shows that real wage growth has slowed in manufacturing in South Africa. Average wages grew faster between 2005 and 2011 in all sub-divisions of manufacturing, with the only exception being wood products and paper.
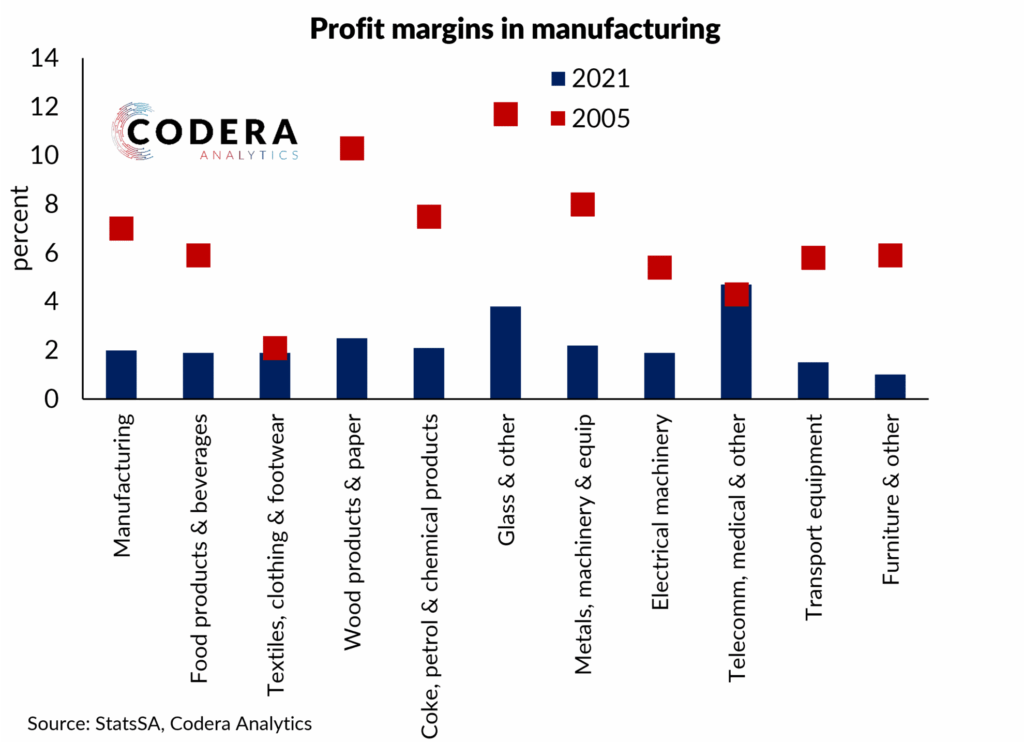
Finally, profit margins suffer too. Profit margins in South Africa’s manufacturing industry declined from 7% in 2005 to 2% in 2021. The Telecommunications division had the highest profit margins in 2021.